Prices Are Rising Faster Than Paychecks: Why Investing Can’t Wait
Groceries, gasoline and everyday essentials are rising faster than wages in Ontario. Here is what the latest Canadian data shows, and why saving alone can no longer keep your money ahead of the cost of living.
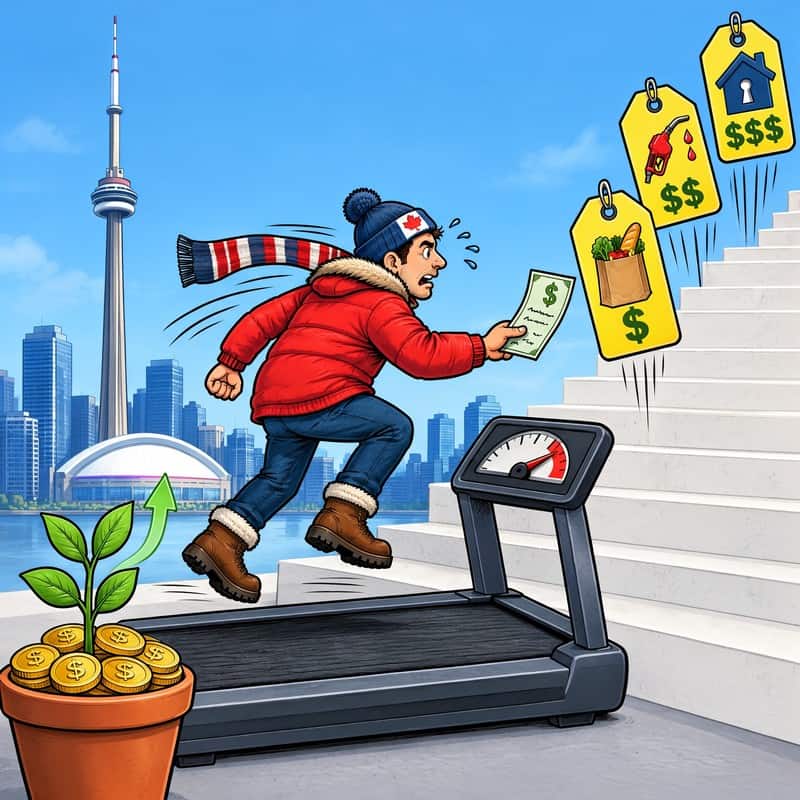
Over the past month, one theme has run through almost every Canadian money headline: life is getting more expensive, and paychecks aren’t keeping up. Canadians are skipping meals, trimming holiday budgets and borrowing to pay for their kids’ activities.
Each of these stories is a cost-of-living problem on its own. Taken together, they raise a bigger question: if your income can’t keep up, what can?
1. Prices: Everyday essentials are leading the way
Statistics Canada reported on November 16 that inflation held at 3.1% in October. The headline number hides how much faster the essentials have climbed.
| Item | Year-over-year change |
|---|---|
| Gasoline (October CPI) | +30.9% |
| Basic grocery basket, family of four (Windsor-Essex, 2026) | +8.15% |
| Food from stores (October CPI, national) | +2.0% |
| Overall CPI (October) | +3.1% |
In Windsor-Essex, feeding a family of four a basic healthy diet now costs about $294 a week, or $1,277 a month. That adds up to more than $15,300 a year before a single restaurant meal. Based on the 8.15% increase, the same basket costs roughly $96 more per month, or about $1,150 more per year, than it did last year.
The Bank of Canada expects inflation to stay above 3% through much of 2027. It raised its policy rate to 2.5% on October 28, its first hike in more than three years.
2. Paychecks: Wages are falling behind
Now compare those prices with what people earn.
| Amount | |
|---|---|
| Ontario minimum wage (from October 1, 2026) | $17.95/hour (+2.0%) |
| Greater Toronto living wage (2026) | $27.60/hour |
| Gap per hour | $9.65 |
| Gap per year (full-time, 35 hours a week) | About $17,563 |
The minimum wage rose about 2% this year, while gasoline rose about 31% and Ontario’s basic grocery basket about 8%. The same Windsor-Essex report shows how tight that leaves a household budget: a low-income family of four earning $2,989 a month has only about $473 left after rent and food. That $473 has to cover utilities, transportation, phones, childcare, clothing and medicine.
3. How Canadians are coping: Cutting back and borrowing
The squeeze shows up in nearly every recent survey:
- 31% of Canadians have cut back on or skipped meals because of the cost of living, rising to 41% among younger Canadians (Salvation Army).
- 24% of households in Windsor-Essex experienced food insecurity in 2025 (Windsor-Essex County Health Unit).
- 30% of parents cut other spending to pay for their children’s activities, and 14% went into debt (Nanos Research for CTV News).
- Canadians’ average holiday budget fell to $1,305, down 14% from $1,521 and the lowest Deloitte has recorded. 34% say their household finances are worse than a year ago (Deloitte Canada).
- Average non-mortgage debt reached $28,118 per consumer, and 90-day delinquency rates on auto loans, credit cards and instalment loans hit a 10-year high (TransUnion).
Belt-tightening has limits. Once the restaurant meals, vacations and gifts are gone, there isn’t much left to cut.
4. The hidden cost: Cash loses value every year
Inflation doesn’t only raise prices. It also quietly shrinks the value of money that sits still.
| Scenario | Result |
|---|---|
| $100,000 in cash, 20 years at 3% inflation | Buys what about $55,400 buys today |
| Time for cash to lose half its purchasing power at 3% inflation | About 23 years |
With the Canadian economy expected to grow just 1.0% this year and per-capita growth only about 0.5% (KPMG), waiting for a big raise to fix the problem is a risky plan.
5. Why starting now matters
The same math works in your favour when you invest. Here is what time and compounding can do with identical monthly contributions.
| Investing $500/month for 25 years | Total contributed | Ending value |
|---|---|---|
| Kept in cash (0% return) | $150,000 | $150,000 |
| Earning 3% per year | $150,000 | About $223,000 |
| Earning 6% per year | $150,000 | About $346,500 |
On the same contributions, the difference between doing nothing and investing steadily for 25 years can be nearly $200,000. The earlier you start, the more of the work compounding does for you.
AiF Insight: Saving protects today, investing protects tomorrow
Cutting costs is the right first response to rising prices, but it is a defensive move. Once the extras are gone, the only lasting way to keep up is to make your money grow faster than your cost of living.
A practical order of operations:
- Know your numbers. List your fixed costs, such as housing, food, transportation and childcare, and compare them with last year. That is your personal inflation rate.
- Clear high-interest debt first. Credit cards at 20% or more work against you faster than almost any investment can work for you.
- Keep an emergency fund. Three to six months of expenses keeps a surprise bill from turning into new debt.
- Put the rest to work, consistently. Use tax-advantaged accounts such as the TFSA and RRSP, invest for the long term and stay diversified. Steady monthly contributions matter more than perfect timing.
Prices will keep moving. The real question is whether your money is moving with them.
Sources: Statistics Canada (November 16, 2026); Windsor-Essex County Health Unit; Ontario Living Wage Network; Bank of Canada; Deloitte Canada 2026 Holiday Retail Outlook; Salvation Army; Nanos Research/CTV News; TransUnion; KPMG Canada Fall 2026 Economic Outlook.